Introduction
The European Union (EU) has set ambitious goals for the energy transition, targeting at least a 55% reduction in greenhouse gas emissions from 1990 levels by 20301. Achieving these goals necessitates a significant shift towards renewable energy sources for electricity production and the electrification of high-emission sectors such as transportation and heat production. This transition presents significant challenges for Transmission System Operators (TSOs) and Distribution System Operators (DSOs), as the existing electrical infrastructure was not designed to handle the variable and bidirectional power flows associated with renewable energy sources.
In this context, grid-scale flexibility and energy storage systems emerge as critical solutions to tackle these challenges2. Energy storage systems can store excess energy and discharge it when needed, addressing issues such as grid imbalance, overvoltage, and congestion3–5. Besides, demand-side flexibility allows consumers to adjust their energy consumption in response to the grid’s necessities, helping to solve/prevent overload and overvoltage issues6–8.
In the current state of the art, the full potential of both technologies is not completely exploited, as their widespread adoption is facing several obstacles, including technological, market, and regulatory challenges.
The Horizon-Europe project SINNOGENES (Storage INNOvations for Green ENErgy Systems)9 aims to address these obstacles by promoting the development and integration of innovative grid-scale energy storage technologies and demand-side flexibility services. From within the SINNOGENES framework, this research work seeks an answer to the questions concerning the maturity of grid-scale flexibility services across Europe. To address this question comprehensively, a three-step approach is followed:
1. Review of significant technologies: the most significant utility-scale flexibility and energy storage technologies are reviewed to understand their capabilities and limitations.
2. Regulatory framework analysis: the current state and future trends of the regulatory framework for grid-scale flexibility services are assessed, with special focus on cross-border balance.
3. Stakeholders’ insights analysis: a set of surveys and interviews with stakeholders in the European energy sector are conducted to gain a thorough understanding of their perspectives on flexibility services.
Following from the above, this work provides an extensive and comprehensive assessment of the current state of grid- scale flexibility services, an identification of key barriers to their widespread adoption and offers insights into the future development of these services.
The rest of this paper is structured as follows. In the first section, the most significant utility-scale flexibility and energy storage technologies are reviewed to understand their capabilities and limitations. The second section analyses the current state and future trends of the regulatory framework for grid-level flexibility services, focusing on cross-border balance. The third section presents the stakeholders' perspectives on flexibility services, based on the analysis of survey results from forty-four stakeholders in the European energy sector, and insights from several bilateral interviews conducted with European companies and organizations in the energy sector.
Methods
This work employs a multi-method approach to evaluate the maturity of grid-scale flexibility services in Europe. The methodology is structured into three main phases: i) grid-scale energy storage and flexibility technologies review, ii) flexibility services regulatory framework analysis and iii) stakeholders’ insights analysis. Each phase is designed to gather comprehensive data to answer questions concerning the maturity of grid-scale flexibility services across Europe and is briefly described below.
1. Grid-scale energy storage and flexibility technologies review
Provides a thorough review of existing literature on grid-scale flexibility and energy storage technologies. Academic journals, industry reports, and technical papers are analysed to identify the most significant technologies, their operational features, and their current state of deployment. As an outcome, this review provides a foundational understanding of the technological landscape and informed subsequent phases of the research.
2. Flexibility services regulatory framework analysis
Focuses on analysing the current state and future trends of the regulatory framework for transmission-system-level flexibility services across Europe. Key EU directives and national regulations from five countries (Spain, Portugal, Germany, Cyprus, and Switzerland) are examined. This analysis aims at identifying regulatory barriers and best practices that influence the adoption and integration of flexibility services. Two main aspects are analysed:
a. EU transmission systems: The analysis covers major EU regulations including the Clean Energy Package, which consists of several directives and regulations that shape the electricity market framework. Specific attention is given to how these directives promote or hinder the deployment of flexibility services and energy storage technologies.
b. Best practices in EU countries: By comparing the regulatory environments of different EU countries, the study highlights best practices and lessons learned from each context. This comparison helps to understand the diverse regulatory landscapes and the impacts on flexibility services' maturity.
3. Stakeholders’ insights analysis
The third phase gathers qualitative and quantitative data from stakeholders within the European energy sector through surveys and interviews10. This phase aims to capture the perspectives and experiences of a diverse range of stakeholders, including TSOs, DSOs, energy producers, industrial consumers, and policymakers.
a. Survey: An online survey was conducted to gather insights from stakeholders within the European energy sector. The survey included 20 questions addressing various aspects of flexibility services, such as technological relevance, regulatory challenges, market dynamics, and user requirements. The survey was distributed to a diverse group of 44 stakeholders, including TSOs, DSOs, energy producers, industrial consumers, and policymakers. The survey results were analysed to identify common themes and stakeholder perspectives on the maturity of grid-scale flexibility services.
b. Interviews: Detailed bilateral interviews with selected stakeholders from the survey group have been conducted. These interviews aimed to delve deeper into the insights gathered from the survey and explore specific issues in more detail. The interview questions covered practical experiences with flexibility services, the impact of government policies, financial incentives, and perceived barriers to adoption. The qualitative data from these interviews provided a richer context to the survey findings and highlighted the nuanced challenges and opportunities in the sector.
Eventually, data collected from the surveys and interviews are systematically analysed by using both quantitative and qualitative methods. Statistical analyses are performed on the survey responses to identify trends and correlations. Thematic analysis is used to interpret the qualitative data from the interviews, enabling the identification of key themes and patterns. This comprehensive analysis provides a robust understanding of the current maturity level of grid-scale flexibility services and the factors influencing their development.
Grid-scale energy storage and flexibility technologies review
As already discussed in the introduction, flexibility refers to the possibility to adjust the balance between consumption and generation of an energy system within a specific timeframe. In particular, flexibility can be offered as a service in response to a price or an activation signal emitted from the system operator. From the perspective of transmission systems, utility-scale storage systems and utility-scale demand response mechanisms are expected to take the leading role in flexibility provision, although industrial thermal storage, hydrogen and large fleets of aggregated Electric Vehicles (EVs) could either contribute. Indeed, for future fully decarbonized energy systems, the bespoke sectors will need to be strongly coupled, providing flexibility by exchanging energy between each other. A summary of the main sources of utility-scale flexibility is provided in the following subsections. A more summarized breakdown can be found in Figure 1.
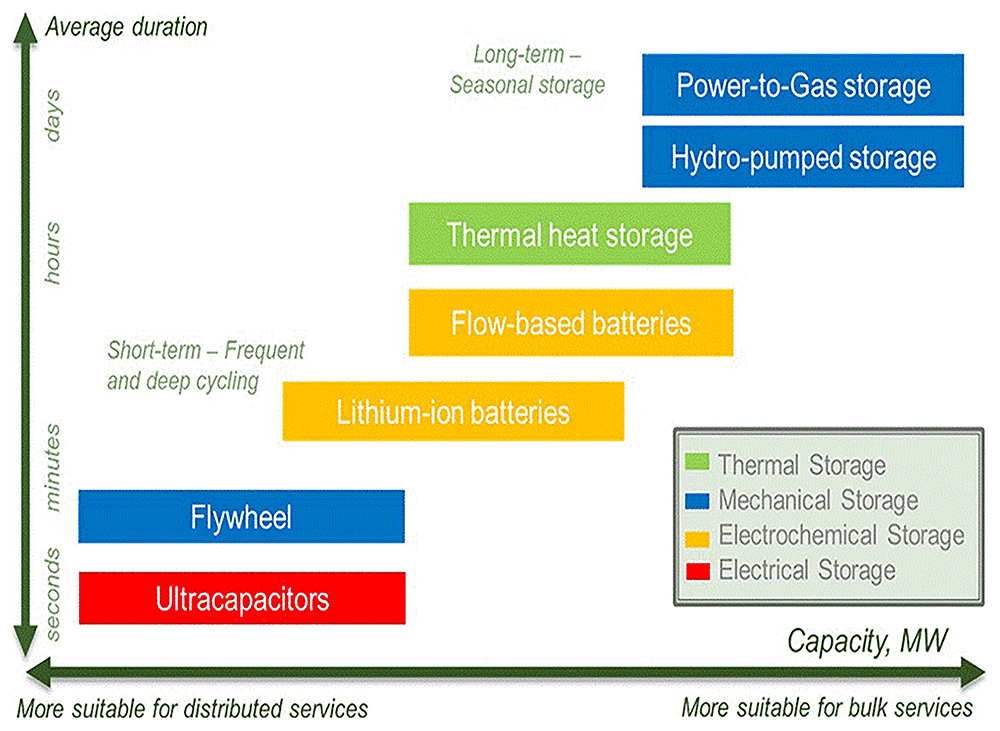
Figure 1. Technology stack of innovative energy storage systems of the SINNOGENES project.
This figure has been reproduced with permission from Nena Apostolidou.
Energy storage
Nowadays, there exist many sorts of storage systems; the most popular are presented in the following:
Battery Energy Storage System (BESS). BESS represents the most widely implemented storage system and is widely utilized not only to store surplus energy production but also to efficiently provide ancillary services, such as black start or serve as main source of a microgrid in case of islanded operation. The most well-known types of BESS are lithium-ion and lead-acid, although Zinc-air and redox flow batteries are currently attracting more and more attention11.
Vehicle-to-Grid (V2G). V2G is also a battery-based solution. In this case, the concept is to utilize the batteries of large fleets of aggregated EVs as a bidirectional storage unit. Of course, this implies that owners need to be compensated for the services provided to the system operator12.
Supercapacitor. A supercapacitor is characterized by a lower energy density than a battery, although it also features higher power density, response time and number of cycles. Consequently, it is often utilized for energy storage undergoing frequent charge/discharge cycles of high current and short duration13.
Electrolyzers and fuel cells. An electrolyser is a device capable of converting electricity into hydrogen, whereas a fuel cell converts the chemical energy of a fuel, usually hydrogen, into electricity. Both technologies are considered to have high energy and power density, which is also reflected in their cost, although their efficiency remains relatively low14.
Closed-loop pumped storage. Consists of two water reservoirs, either natural or artificial, located at different altitudes. Then, in case energy production is higher than demand, surplus power is used to pump water from the lower reservoir to the higher. In the other way around, when production is lower than demand, water is released from the higher reservoir to the lower one to produce electricity15.
Compressed air. The concept of compressed air storage is similar to that of pumped storage. More specifically, in this case electricity is used to compress air and store it, often in underground caverns. Once the demand is higher than the production, the pressurized air is released to generate electricity through an expansion turbine generator16.
Flywheels. A flywheel is a mechanical type of energy storage, where surplus production is stored as kinetic rotational energy. When energy is needed, the spinning force is used to activate a generator. Although this technology is characterized by fast response time and high-power density, it also features relatively high self-discharge rates (hours instead of days or months), unless a very deep vacuum is used17.
Thermal energy storage. Electricity can be used to produce thermal energy by means of the so-called Power-to-Heat (P2H) devices, which is subsequently stored in a thermal energy storage until it is needed.
Hydrogen storage
Underground Hydrogen Storage (UHS) refers to the practice of storing hydrogen gas in underground reservoirs or caverns for later use. It is an important component of hydrogen-based energy systems and will play a crucial role in ensuring a reliable and continuous supply of hydrogen. By means of a combination of electroliers and fuel cells, making the system reversible, UHS is key for ensuring a stable and reliable supply of hydrogen. Broadly speaking, UHS can be located in different geological underground sites, such as salt caverns, aquifers and depleted gas/petroleum fields18.
Utility-scale demand response
Demand Response (DR) can be referred to as a voluntary reduction or shift of electricity use by customers in response to an external incentive18,19. In this way, DR can be considered as a form of “virtual storage”, since it provides many of the same flexibility services as energy storage technologies by shifting or curtailing demand rather than storing energy. In other words, DR can contribute to frequency regulation, peak shaving, congestion management, and reserve capacity in a way that is functionally equivalent to storage, although through different mechanisms. Hence, DR complements storage by reducing the need for additional capacity. This equivalence also explains why stakeholders in this study consistently ranked electrochemical storage and DR as the two most relevant flexibility sources. Further into detail, there exist two types of DR programs::
Implicit DR. Time-varying electricity prices are used to encourage consumers to shift their loads in accordance with the system’s needs.
Explicit DR. Users participate in energy or flexibility markets and modify their consumption based on the results of the bids. Alternatively, one-time incentives named tokens can be offered to customers to modify their consumption.
With regards to the flexibility services provision at transmission-system level, different types of users can provide them through DR schemes in different timescales. A summary is provided in Table 113.
Table 1. Transmission-system-level flexibility services through utility-scale demand response, users and timescales.
| User | Flexibility service | Timescale |
|---|
Industrial Customers Aggregators of loads at distribution-grid-level Aggregators of EVs at distribution-grid-level
Electrolysers |
Balancing unpredictable abrupt load/generation changes |
Seconds |
| Aggregators of loads at distribution-grid-level Aggregators of EVs at distribution-grid-level | Balancing load/generation forecast errors | Minutes |
| Industrial Heat Storages | Balancing daily variability in net load | Hours/Days |
| Hydrogen | Balancing seasonal energy availability | Months |
Overall, the reviewed technologies show varying degrees of maturity and suitability for grid-scale applications. Building on recent European maturity assessments20, it becomes clear that maturity must be understood in terms of deployment along with performance against key indicators such as lifetime, efficiency, scalability, and cost. A summary is provided in Table 2. As shown, pumped hydro and lithium-ion batteries are at the highest TRL (8–9), already commercially deployed at scale, while compressed-air and thermal storage are at intermediate TRLs (6–7) with significant improvement potential by 2030. Hydrogen, power-to-X and demand response technologies currently remain at lower maturity levels but are expected to scale rapidly, with scenarios of 40 GW of electrolyser capacity installed in Europe by 2030. Conversely, supercapacitors and flywheels remain niche solutions, providing unique advantages only in fast-response applications.
Table 2. TRL maturity assessment of the different energy storage systems (adapted from 20).
| Technology | TRL | Services |
|---|
| Pumped hydropower storage | 9 | Long-term energy storage
Dispatchable synchronous generation (inertia and voltage control) |
| CAES | 7 | Long-term energy storage
Dispatchable synchronous generation (inertia and voltage control) |
| BESS | 9 | Medium-term energy storage
Daily cycle |
| Flywheel | 7 | Short-term power-frequency control |
| Supercapacitors | 8 | Short-term power-frequency control |
| SMES | 8 | Short-term power-frequency control |
In conclusion, grid-scale flexibility in Europe cannot be achieved by a single dominant technology but rather through a complementary portfolio. Electrochemical and mechanical storage can address short- to medium-term needs, while hydrogen and sector coupling will be crucial for long-term decarbonization. Future deployment should therefore prioritize commercially mature solutions in the near term, such as lithium-ion and demand response, while accelerating research, demonstration, and investment in alternative battery technologies, as well as hydrogen-based and long-duration technologies.
Flexibility services regulatory framework analysis
In order to allow utility-scale storages and DR programs to provide flexibility services, an adequate regulatory framework that facilitates their participation in the electricity markets and ancillary services is necessary. This regulatory framework must ensure free competition and equitable participation to all flexibility providers, as well as establishing a clear role for Transmission and Distribution System Operators (TSOs and DSOs) for an active system management.
The objective of this section is to analyse the current state and future trends of the regulatory framework for transmission- systems-level flexibility services in the European context and compare experiences and best practices of different countries. To this end, the existing legislation and regulation is reviewed, as well as the proposals and ongoing projects in this field, firstly at EU-level and subsequently country by country.
ENTSO-E European regulatory framework for transmission-systems-level flexibility services
At European level, the ENTSO-E has adopted measures with the objective of promoting the transition from fossil fuels to cleaner energies. In 2019, it promoted the "Clean Energy Package" (CEP), which consists of four regulations:
Regulation on risk-preparedness in the electricity sector (EU) 2019/941,
Regulation establishing a European Union Agency for the Cooperation of Energy Regulators (EU) 2019/942,
Regulation on the internal market for electricity (EU) 2019/943,
Directive on common rules for the internal market for electricity (EU) 2019/944.
The general regulatory framework encompassing the flexibility aspects, namely: actors, definitions and motivations, is summarized in 21, which sets out the general rules for generation, transmission, distribution, and storage, with the aim of creating a customer-centric, transparent, and fair market. In the particular case of energy storage, the directive states that: “Member States shall ensure that active customers that own an energy storage facility:
have the right to a grid connection within a reasonable time after the request, provided that all necessary conditions, such as balancing responsibility and adequate metering are fulfilled,
are not subject to any double charges, including network charges, for stored electricity remaining within their premises or when providing flexibility services to system operators,
are not subject to disproportionate licensing requirements or fees,
are allowed to provide several services simultaneously, if technically feasible”.
Participating in the market as an aggregator is allowed and encouraged. In this regard, Article 17 in its first paragraph states: “Member States shall allow and foster participation of demand response through aggregation. Member States shall allow final customers, including those offering demand response through aggregation, to participate alongside producers in a non- discriminatory manner in all electricity markets.”
Eventually, guidelines for TSOs and DSOs for designing flexibility services to meet the needs of their networks are given, which include:
Optimizing infrastructure investment,
Deferring or avoiding asset reinforcement,
Efficient planning of maintenance, asset replacement, and connection works,
Mitigating the effect of network outages,
Improving the quality of supply,
Reducing network implementation timescales,
Increasing the capacity for new renewable generation.
Europe countries national legislation
Further to the EU-level analysis, in this subsection, current energy and storage regulatory framework for the provision of flexibility services is analysed by making the case of five countries.
Spain. The Integrated National Energy Climate Policy (INECP) is the guideline of Spain climate and energy policy. The plan encloses a number of policy actions that support Spanish climate targets including energy efficiency, renewables, and transport:
23% reduction in greenhouse gases emissions from 1990s levels,
42% renewable in the energy use,
40% improvement in energy efficiency (from 2005 levels),
74% share of renewables in electricity generation.
In this context, energy storage is considered crucial in the energy mix, as it provides dispatchable assets to provide flexibility services to the transmission grid. There are currently some barriers in the deployment of the energy storage systems in Spain, due to the lack of definition of administrative procedures and criteria for project permits. Nevertheless, these have been addressed in Measure 1.5 of the Energy Storage Strategy published in 2021, to define the regulatory framework for storage and simplify permits issuing. In the Law 7/2021 of May 20 on climate change and energy transition, the Long Term Decarbonization Strategy and the Storage Strategy anticipate the development of new regulations applicable to storage on the following matters:
development of the legal regime for storage holders,
simplification of administrative procedures and the reduction of administrative burdens,
modification of the system operator's operating procedures to include storage,
inclusion of storage in the planning of the electricity transmission grid,
creation of sandboxes in which pilot R&D&I projects are developed.
Likewise, the approval of the Circular establishing the methodology and conditions for access and connection to the transmission and distribution networks in terms of electricity demand, as well as its detailed specifications, applicable to storage facilities when they behave as demand facilities, is expected.
Portugal. Since 2016, Portugal is committed to achieve carbon neutrality by 2050, under the Roadmap for Carbon Neutrality 2050 (RNC 2050). This goal was further outlined in 2019 when the National Energy and Climate Plan 2030 (PNEC 2030) was approved. Then, additional legislation was approved in January of 2022 in the DL 15/2022 implementing a transposition of EU directives 2019/944 on the common rules for the internal market for electricity and 2018/2001 on the promotion of the use of renewable energy sources.
Additionally, DL 15/2022 anticipates that storage facilities may be operated as an independent system or as an additional facility integrated within self-consumption or generation plants within the network. They can also operate in different simultaneous activities within the electrical system. This allows storage facilities to interact in the primary electricity market and to be considered for reserve requirements and flexibility services.
DL 15/2022 also dictated that the regulator must create regulations for the operation and access to the network of storage facilities, which was delivered by ERSE in the regulation Nº 4/2023. A key challenge in implementing the DL 15/2022 for energy storage policies lies in the lack of local expertise, which is hindering storage integration in the grid.
The regulator ERSE also launched in 2019 a dynamic tariff pilot project focused on the participation of the demand on the system services market for a full year, which led to recommendations as a way of improvement to the previous legislation of 2017, such as the shift from 1h to 15min integration periods and the simplification of the process of new market agents affiliation and to the evaluation of the market agents and their fulfilment of accepted bids and incurrent penalties.
Germany. The energy transition poses significant challenges for Germany's electric networks, necessitating efficient and intelligent linking of grids, generation, and consumption. The German Energy Act (EnWG) aims to address these challenges with several key objectives:
Ensuring the electricity grid networks can fulfil their transport tasks.
Providing sufficient generating capacity to meet future energy consumption predictions.
Maintaining network integrity through reliable control mechanisms, even when network input and output volumes are not balanced.
Protecting the networks from third-party interventions.
Regarding "Flexibility in the power supply system," the Bundesnetzagentur has initiated discussions to identify obstacles and propose approaches to enhance flexibility development. Key propositions include:
Firm adherence to competitive solutions that respond to market price signals.
Explicit rejection of specific support for individual players in the electricity market.
Eliminating market distortions caused by special support schemes to improve access to flexibility options, making the system more efficient and less expensive.
Currently, there is no specific legislation for electricity storage facilities in Germany. These facilities are considered consumers of electricity, meaning they must pay all associated consumption fees and charges when withdrawing electricity from the grid for storage purposes. However, several exemptions aim to facilitate storage facility use. Notably, the EnWG exempts storage facilities built after December 31, 2008, and operational within 15 years after August 4, 2011, from network tariffs for 20 years when withdrawing electricity. This exemption applies if the withdrawn electricity is stored in an electrical, chemical, mechanical, or physical storage facility and is re-fed into the same electrical system after a delay.
Securing electricity supply primarily requires balancing generation and consumption at all times, ensured through the electricity market. Therefore, flexibility in energy supply involves interactions with neighbouring electrical systems, with cross-border interconnectors playing a crucial role. Additional policies are being considered to ensure a flexible electricity supply system.
Cyprus. Currently, the electricity market in Cyprus does not support flexibility services, aggregation, or demand response. These services will be enabled through a fully functioning Competitive Electricity Market (CEM), planned to become operational in the coming years. Currently, only RES-only generation aggregation is allowed, with capacities ranging from a minimum of 1 MW to a maximum of 20 MW. A new proposal seeks to expand the aggregation scope to include various generation sources, storage systems, and demand response.
Demand response is not expected to be implemented initially due to the market's immaturity.
Regarding storage, Cyprus has an estimated 130 MW of pumped storage potential by 2030. According to a decision by the Cyprus Energy Regulatory Authority (CERA), storage systems installed above the metering point and not combined with local electricity consumption could participate in the Wholesale Electricity Market. These storage systems will not be charged for grid use during the charging cycle. Additionally, specific products for high-performance ancillary services, such as fast primary regulation and synthetic inertia, could be defined and remunerated through a “pay-for-performance” scheme.
Switzerland. Although Switzerland is not a member of the European Union nor the European Economic Area, it has been included in this survey as it is a member of the EFTA (also referred to as European “single” or “internal” market) and holds several bilateral and multilateral treaties both with the EU and Member States.
The legal framework governing Switzerland's energy sector is multi-layered. At its foundation is the Swiss Constitution, which under "Section 6 Energy and Communications" (articles 89 to 91) lays down specific principles for the energy sector. This is supported by several federal laws, such as the Energy Act (EnG), CO2 Act, Electricity Supply Act (StromVG), and Electricity Act (EleG). Additionally, there are various federal ordinances like the Energy Ordinance (EnV) and CO2 Ordinance, along with others, including the Electricity Supply Ordinance (StromVV).
Further into detail, in Swiss regulations and policies there is a preference for self-regulation instead of public regulation. At cantonal and communal level, there exist distinct energy laws and regulations. For instance, Zurich has its "Energiegesetz." However, it is important to note that electricity supply primarily falls under federal competence.
Switzerland’s hydro assets are often highlighted due to their important contributions to flexibility, and, in fact, represent the main flexibility contributors in daily and weekly timeframes, even exceeding national needs by a factor of 2 to 3. The chart of Figure 2 depicts flexibility contributions per technology in daily, weekly and seasonal timeframes projected in current and future scenarios.
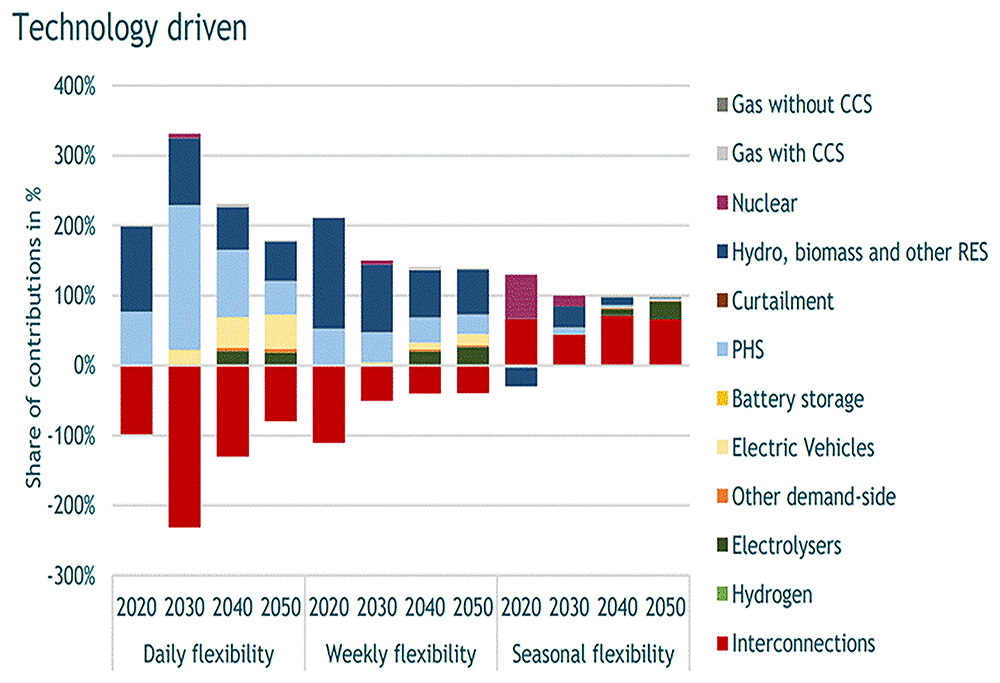
Figure 2. Share of technologies providing flexibility in Switzerland.
This figure has been reproduced with permission from Artelys (Available here).
Summary. Table 3 provides a comparative analysis of national energy and storage legislation of the surveyed countries; to offer a summary of the different policies and strategies each country employs to integrate energy storage and flexibility services and highlight differences and similarities in regulatory frameworks.
Table 3. National energy and storage legislation across five European countries.
| Country | Energy policies and regulations | Barriers |
|---|
| Spain | Law 7/2021 of May 20:
• Development of the legal regime for storage holders
• Simplification of administrative procedures and the reduction of administrative burdens
• Modification of the system operator’s operating procedures to include storage.
• Inclusion of storage in the planning of the electricity transmission grid
• Creation of sandboxes in which pilot R&D&I projects are developed. | Barriers in the deployment of energy storage systems, due to the lack of definition of administrative procedures and criteria for project permits. |
| Portugal | DL 15/2022:
• Storages facilities may be operated as an independent system or as an additional facility integrated within self-consumption or generation plants within the network.
• The regulator must create regulations for the operation and access to the network of storage facilities, which was delivered by ERSE in the regulation Nº4/2003. | Lack of local expertise in energy storage policies, which is hindering storage integration in the grid. |
| Germany | There is no specific legislation on electricity storage facilities. German law regards electricity storage facilities as consumers of electricity.
One exemption is included in the EnWG for storage facilities built after 31 December 2008 and put into operation within 15 years on or after 4 August 2011. These facilities are exempted from the duty to pay network tariffs for a period of 20 years when withdrawing electricity from the grid. |
Challenges in the security of supply, reliability of transmission systems and sufficiency of generation capacity, due to the growth in European electricity trading and the volatility of renewable generation. |
| Cyprus | CERA, Cyprus Regulatory Authority:
• The storage systems installed upwards the metering point and not combined with local consumption of electricity could potentially participate in the Wholesale Electricity Market.
• The storage systems will not be charged for use of the grid during the charging cycle.
• Specific products for high performance ancillary services could be defined, to be provided by storage systems and remunerated according to a “pay-for-performance” scheme. | Lack of flexibility services and aggregators in the current electricity market.
Demand response not even foreseen in the near future, due to market immaturity. |
| Switzerland | Not a member of the EU or the EEA but influenced by EU agreements.
Multi-layered legal framework, federal laws, and cantonal regulations governing the energy sector.
Swiss regulations and policies there is a preference for self-regulation instead of public regulation. Emphasis on hydro assets for flexibility and challenges in integrating with European electricity markets. | Challenges in the integration with the European electricity markets, due to the lack of agreement between Switzerland and EU.
Political and legal uncertainties hindering accession to the cross-border balancing energy platforms. |
Review of cross-border balance services
For what concerns the definition of flexibility services, it is important to highlight the difference between distribution-and transmission systems. In fact, for the former, flexibility is a relatively new concept, and the provision of flexibility services points towards the creation of local flexibility markets, where customers participate as sellers and DSOs as buyers. On the other hand, at transmission-system level, the provision of flexibility services translates into the possibility for flexibility providers to join the balance services markets. These last are those devoted to balancing supply and demand to ensure security, quality, and efficiency of the supply. Balance services can be classified into three types: adjustment, reserve, and net balance services.
Are those that allow system operators to modify the scheduling of generation and consumption to adapt to the actual conditions of the system, such as demand variations, contingencies, or deviations. Adjustment services can be performed through market bids or bilateral contracts.
Are those that provide additional generation or consumption reduction capacity to be activated in case of need to maintain the system balance. Reserve services can be divided into primary, secondary and tertiary reserves, depending on the response time and duration required.
Are those that allow market agents to compensate for their deviations between scheduled and actual energy by exchanging energy with other agents. Net balance services can be performed through centralized or decentralized mechanisms, depending on the degree of coordination between agents.
Cross-border balance services exchange platforms
In the past, each country managed its own balancing services at a national level, with different rules, requirements, and prices, which limited competition, efficiency, and integration of the internal electricity market. Moreover, it impeded the exploitation of the full potential of renewable sources and distributed resources of each country. Consequently, there is currently a growing interest to provide balanced services at both national and cross-border level. Indeed, according to a study conducted by the European Commission, the annual saving estimated by the integration of balancing services could reach one billion euros in 2025.
Cross-border balance services are provided through exchange platforms, i.e., computer systems that facilitate cross-border trade of energy for balance services between system operators, with the aim to integrate the balance markets of the member countries of the European Union.
TERRE. This platform facilitates the exchange and optimization of a substitute reserve energy standard (RR) among electric network operators. The substitution reserve, as part of the tertiary regulation, is an additional service that involves voluntary adjustments in the production or consumption of enabled facilities. The platform makes use of a centralized software called LIBRA, which centralizes the available offers of balance energy and provides an optimal allocation to meet the imbalance needs of the system operators.
MARI. The platform was created for the exchange of balancing energy of the Manual Frequency Restoration Reserves (mFRR) type between the network operators of different countries, with the aim of increasing the efficiency and integration of the electricity market. Both the tertiary reserve service and the MARI platform are based on the same type of reserves (mFRR), which are resources that can be manually activated by the system operator to restore the reserve used in secondary regulation, within a maximum period of 15 minutes from the request.
PICASSO. This platform was designed for the international coordination of frequency restoration reserves with automatic activation and stable system operation. This program allows the coupling of national balancing markets for frequency restoration reserves with Automatic Frequency Restoration Reserves (aFRR), which are a type of secondary reserve that is activated automatically within 15 seconds and maintained for a maximum of 15 minutes to restore the frequency of the electrical system.
Because of the sheer installed volume and their role in the system balancing, electricity storage modules have an increasing significance for the power system. Designed properly, they possess the capability to provide several grid supporting functions without significant cost implications. While the current structure of Regulation (EU) 2016/631 of 14th of April 2016 “establishing a network code on Requirements for grid connection of Generators” (“Requirements for Generators”, NC-RfG)22 and Regulation (EU) 2016/1388 of 17th of August 2016 “establishing a network code on Demand Connection” (“Demand Connection Code”, NC-DCC)23 remain, profound amendments as well as new articles were introduced in the attempt to address the impacts of new developments in the electric power and transport sectors, such as electricity storage24. Highlights on Gaps in the RfG Network Codes Regarding the Inclusion of Storage:
Lack of Comprehensive Provisions for Storage: The current RfG and DCC network codes do not fully integrate storage requirements, leading to inconsistent application across different Member States (MS). Some MS have already developed their own regulations, but there is no harmonized approach at the EU level, which could lead to market fragmentation.
Frequency Response Gaps: While provisions exist for how storage should respond to frequency drops in emergencies, there are no clear guidelines on how storage should behave as frequency recovers. This lack of clarity can lead to unintended and unhelpful behaviours during frequency recovery, complicating the management of grid stability by Transmission System Operators (TSOs).
Need for Harmonization with Existing Standards: Integration of storage into the RfG and DCC should not overlook the relevance of existing standards such as EN 50549-1 & -225. There is a need to harmonize new requirements with these established technical specifications to ensure consistency and avoid redundant or conflicting regulations.
Application of New Type A Requirements to Storage: New Type A requirements for power-generating modules (PGMs) should also apply to storage units. This includes capabilities for modulating and controlling active power, ensuring that storage units are treated equitably with other network users and existing power plant.
Country-Specific Regulations and Practices: Examples from Italy show that national standards already incorporate storage in terms of technical requirements, connection processes, and functionalities. These experiences can inform the development of EU-wide standards, emphasizing the importance of taking country-specific practices into account during harmonization efforts26.
Clarification for Mixed Customer Sites: There is a pressing need for clear regulations concerning mixed customer sites that include generation, demand, and storage. The current lack of clarity can lead to inconsistent applications and potential discrimination against certain types of distributed resources.
EU stakeholders insights on flexibility: energy industry
SURVEY
Following from the analysis of the current regulatory framework for utility-scale flexibility and energy storage services, in this section, the results of a survey conducted to forty-four stakeholders within the European energy sector are presented, in order to highlight their main highlights and insights. Provided that finding a stakeholder willing to collaborate in the survey is not a simple task, this number is considered to be sufficient and representative of the sector. The survey consists of twenty questions that address different aspects related to the flexibility market, with particular focus on services to be provided at transmission system level, which include definition, benefits, obstacles, solutions and expectations. Questionnaire is reported in the dataset available in 10. Respondents belong to different European countries, and represent different actors of the electricity market, such as network operators, generators, retailers, industrial consumers, regulators, and experts. In the following responses are analysed and the main conclusions drawn. Key survey conclusions are reported in the following.
Flexibility Need/Use. The most relevant data concerning this point are those illustrated in Figure 3 and can be summarized as follows: 77% of stakeholders express a need for or actively use flexibility in their regular activities. Notably, industrial consumers exhibit a lower percentage, i.e. 50%, indicating varied perspectives across sectors.
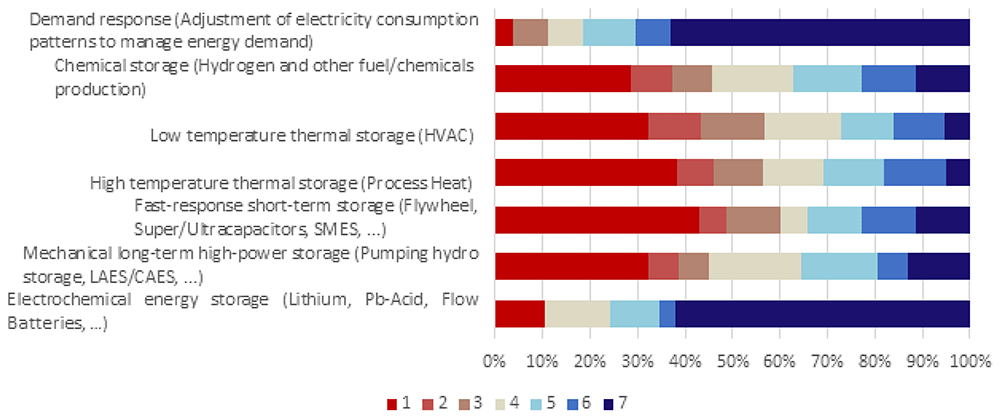
Figure 3. Relevance in % of storage technologies for the provision of flexibility services.
Technologies Relevance. Electrochemical Energy Storage and Demand Response capture significant interest within stakeholders needing flexibility, as 68% of the interviewees gave them a high score, i.e., 6/7 or 7/7. Conversely, both high- and low-temperature thermal storage are viewed with lesser enthusiasm.
Technical Criteria of Energy Storage. For stationary uses, the significance of energy density as a design factor is minimal, while scalability, lifespan and power-to-energy ratio seem to be the most important ones as over 70% of those surveyed give a score of 6/7 or 7/7. Preferences vary by sector: the electric industry considers power-to-energy ratio as the most important factor, whereas industrial sectors emphasize round-trip efficiency and scalability.
Market Dynamics. Opinions on cost-effective solutions are divided between ownership, 59.1%, and renting, 40.9%, with a preference for decentralized owned assets, as it can be seen in Figure 4. It is important to note that centralised and decentralised solutions are equally preferred.
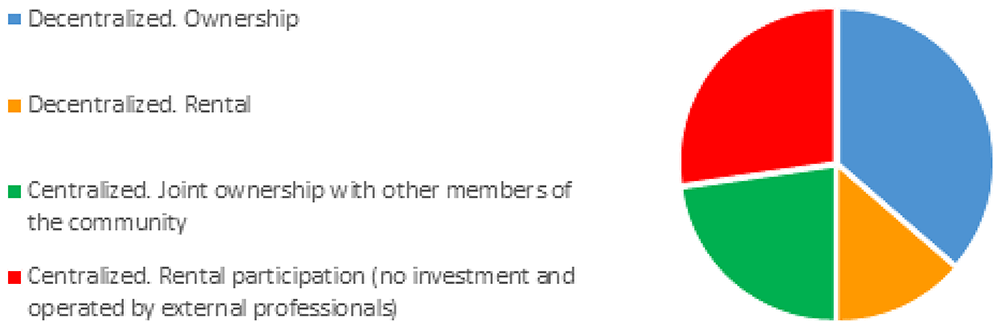
Figure 4. Market dynamics regarding flexibility assets’ ownership and distribution.
Barriers and Incentives. The predominant obstacles to a widespread acceptance of flexibility lie in the perception that benefits do not justify costs and system operators need more freedom to operate flexibility assets. Incentives deemed important by stakeholders include reduced network fees, additional compensation for providing flexibility, and consistent long-term pricing cues.
Consumer Acceptance. For users to embark on provision of flexibility services, the security of IT systems is essential, outweighing concerns over privacy and the management of user data. On the other hand, tools integration and variety is less valued, with an average score about 12% lower than that of security.
SINNOGENES Technologies. The main factors influencing the adoption of these technologies are the costs of investment and operation, alongside the assurance of steady future income. As it can be seen, the biggest challenge to embracing SINNOGENES technologies is the existing regulatory environment, which has been previously analysed in greater depth in the section “Flexibility services regulatory framework analysis”. Contrary to what seen in “Consumer Acceptance” digitalisation, that could include IT security, is not seen as a barrier, with an average score about 22% lower.
Interviews
Energy Consultant. The interviewee began by emphasizing the complexity of the electricity market, highlighting that identifying a lack of understanding is a crucial problem. Consequently, educational campaigns to improve understanding should be proposed, thereby stressing the significance of education in this sector. Furthermore, future challenges include funding and network capacity issues, while emerging opportunities count with the integration of electric vehicles and decentralization. Lastly, the importance of technology has been underscored, with a focus on energy storage, artificial intelligence, and machine learning, which are pivotal in stabilizing the market, reducing prices, and enhancing efficiency.
DSO. The interviewee stressed the importance of policy guidance and the search for more incentives for network investments and renewable resources with storage. Impact of the regulatory framework on the implementation of flexibility technologies has been emphasized, highlighting how policies shape market compatibility. Additionally, attention was turned to network digitalization as a key trend and the need for new IT technologies to control flexibility resources. This perspective demonstrates a proactive approach towards the future and underscores the importance of technology in the sector's evolution. The interviewee anticipates that flexibility technologies will support decarbonization, pointing out the critical role these technologies will play in transitioning to a more sustainable energy system.
Industrial Consumer. The interviewee highlighted the impact of government policies on flexibility, emphasizing the need for clear frameworks for access and interconnection procedures. This underscores the importance of a stable regulatory environment in the energy market. The interviewee also emphasized the development of direct current transmission networks and new high-efficiency batteries for flexibility, showing the relevance of technological advancements in addressing specific sector challenges. Furthermore, the interviewee expressed concerns about the potential cost increase due to investments and the risk of industries relocating, underscoring the need to balance sustainability with economic considerations.
DSO. The interviewee discussed voltage issues and the implementation of pilot projects with batteries to address these challenges, reflecting a practical application of innovative solutions. Country legislation reimburses 100% of flexibility expenses and the development of new regulations, emphasizing the importance of a favourable regulatory framework. Moreover, expectations of significant developments have been expressed in technologies such as vehicle-to-grid charging, classical storage, and hydrogen technology, highlighting the continuous need for innovation.
Renewable Energy Company. The interviewee considered technological advances as key drivers of sector expansion, emphasizing the need for innovation in market mechanisms and platforms. This highlights the dynamic and adaptable nature required for the growth of flexibility in the energy market. The interviewee anticipated a reduction in renewable energy generation limitations, an improvement in network reliability, and emissions reduction, showcasing the positive impact of flexibility technologies. Additionally, the interviewee identified advanced energy storage systems, demand response technologies, predictive analytics, and artificial intelligence as relevant innovations, illustrating the diversity of technologies contributing to market flexibility.
Renewable Energy, Energy Efficiency and Demand Response Company. The interviewee emphasized flexibility as a core approach for renewable energy, storage, and electric vehicles, showcasing a comprehensive energy management strategy. Attention has been drowned to technological barriers, such as the lack of standardization in communication protocols, and emphasized the need for regulations that drive interoperability. Moreover, the interviewee predicted an increase in hourly billing, demand response, and bidirectional charging/discharging of electric vehicles, indicating a forward-looking view and identifying emerging trends in energy management.
Results and discussion
This section discusses the findings from the review of significant technologies, regulatory framework analysis, and stakeholders' insights, offering an integrated perspective on the maturity of grid-scale flexibility services in Europe. The review of significant technologies revealed several key points:
The study identified a wide range of utility-scale flexibility and energy storage technologies, each with unique advantages and limitations. Technologies such as Battery Energy Storage Systems (BESS) and Vehicle-to-Grid (V2G) systems are widely implemented and versatile, providing services like frequency regulation and backup power. Mechanical storage technologies like pumped hydro and compressed air energy storage (CAES) offer large-scale solutions but face geographic and infrastructure limitations.
Innovative technologies such as supercapacitors, flywheels, and hydrogen storage are gaining attention for their rapid response times and potential for long-term energy storage. Hydrogen storage, in particular, shows promise for integrating with renewable energy sources to provide long-term energy solutions, despite current efficiency challenges.
The successful deployment of these technologies requires careful consideration of their integration into existing grid infrastructure. Technologies need to be scalable, efficient, and compatible with other grid components to ensure seamless operation and maximize benefits.
The regulatory framework analysis highlighted several critical issues:
The Clean Energy Package provides a robust foundation for promoting flexibility services and energy storage across Europe. However, the implementation of these directives varies significantly among member states, leading to inconsistencies and barriers in the regulatory landscape.
The study found considerable differences in national regulations, which impact the adoption of flexibility services. For example, Spain and Portugal are proactive in integrating energy storage into their energy policies, while Germany's regulatory environment still treats storage primarily as a load, complicating its market integration.
Regulatory barriers such as complex permitting procedures, lack of compensation mechanisms, and insufficient long-term price signals were identified as significant obstacles. Best practices from countries like Spain, which has clear policies supporting storage integration, provide valuable lessons for other member states.
Insights from stakeholders provided a nuanced understanding of the market dynamics:
A majority of stakeholders (77%) expressed a need for or active use of flexibility services, indicating strong market demand. However, the specific needs and priorities varied across different sectors, reflecting the diverse applications of flexibility technologies.
Stakeholders highlighted electrochemical energy storage and demand response as the most relevant technologies, with 60% of the interviewees assigning them the maximum relevance score. Furthermore, important criteria for technology adoption included power-to-energy ratio, round-trip efficiency, and scalability, with preferences varying by sector, with ownership being preferred to renting (59.1% preference vs. 40.9%).
High implementation costs, perceived insufficient benefits, and regulatory uncertainties are major barriers to widespread adoption. In brief: “benefits do not yet justify the costs.” Hence, stakeholders emphasized the need for regulatory reforms, as well as financial incentives, and clear long-term pricing signals to hedge investment risks.
Emerging trends such as the integration of electric vehicles, decentralized energy systems, and advanced energy management technologies were seen as key opportunities for enhancing grid flexibility. Stakeholders also stressed the importance of educational campaigns to improve market understanding and acceptance of flexibility services.
For a more detailed understanding of stakeholder survey responses, a supplementary document containing all the details has been uploaded to Zenodo10.
Conclusions
This work provided one of the first integrated maturity assessments of grid-scale flexibility and storage services in Europe, combining technological review, regulatory analysis, and stakeholder perspectives attained within the Horizon Europe SINNOGENES project. Findings highlight three overarching insights.
Firstly, the most significant utility-scale flexibility and energy storage technologies have been reviewed, highlighting their pros and cons. Here, lithium-ion batteries and pumped hydro storage have been identified as the most mature technologies (TRL 8-9). Nonetheless, the analysis showed that grid-scale flexibility in Europe needs to be achieved through a complementary portfolio, so that future deployment should therefore prioritise commercially mature solutions in the near term, while accelerating research, demonstration, and investment in alternative battery technologies, hydrogen-based and long-duration technologies.
Secondly, the current state and future trends of the regulatory framework for transmission-level flexibility services were analysed. Despite the existence of EU directives such as 2019/941, 2019/942 and 2019/944, significant barriers remain. Regulatory fragmentation persists, as Member States interpret and implement these directives in heterogeneous ways, creating uncertainty for investors and hindering the development of cross-border markets. Long and complex permitting procedures further delay the deployment of storage projects, while the absence of stable long-term price signals discourages large-scale investment. Moreover, the market design still lacks a clear recognition of storage as a distinct asset class, which limits its full participation in energy and ancillary service markets. To overcome these barriers, the analysis points to three key actions, which are essential to unlock investment and enable flexibility services to contribute effectively to a decarbonised Europe:
harmonising the implementation of EU directives across Member States,
accelerating permitting and authorisation procedures through simplified and transparent frameworks,
ensuring long-term regulatory visibility by creating predictable pricing mechanisms and explicitly recognising storage and demand-side resources as market participants.
Thirdly, stakeholders’ insights about flexibility services have been assessed through a combination of survey and one- to-one interviews, resulting in the following outcomes:
77% of surveyed stakeholders express a need for or actively use flexibility in their regular activities, although this number drops to 50% among industrial users.
Electrochemical Energy Storage and Demand Response emerge as the most interesting sources of flexibility, with 60% of the interviewees assigning them the highest relevance score (7/7)
Electric industry considers power-to-energy ratio as the most important technical criterion to choose a storage system, whereas industrial sectors favour round-trip efficiency and scalability,
Decentralized owned assets emerge as the most cost-effective solution, with ownership being preferred to renting (59.1% preference vs. 40.9%).
In brief, the predominant obstacle to a widespread acceptance of flexibility lies in the perception that benefits do not justify costs.